

DAR ES SALAAM — Tanzania’s capital markets are entering a potentially important period of change as the Government widens access to government securities, prepares selected state owned enterprises for possible listing on the Dar es Salaam Stock Exchange and puts in place new tools intended to support a more developed financial market.
The changes have not happened all at once. They form part of a gradual effort to broaden participation in Tanzania’s financial markets and create more options for raising long term capital. For investors, both within Tanzania and outside the country, they also raise questions about what new opportunities could emerge as the market develops.
The Capital Markets and Securities Authority reported in August that total investment in Tanzania’s capital markets had increased during the financial year ending June 2026. Investor participation and activity in the primary and secondary markets also grew, while the range of available products continued to expand through bonds, sukuk and investment funds.
Attention is now turning to what comes next, particularly as Tanzania seeks to attract a wider pool of investors and bring more state owned enterprises into the capital market.
Tanzania widens the investment pool
One of the more significant developments came in August when the Bank of Tanzania published amendments to the country’s Foreign Exchange Regulations. Under the previous 2022 regulations, non resident participation in Tanzanian government securities was restricted to residents of prescribed territories and Tanzanians living in the diaspora.
The 2026 amendments widen access to the government securities market, creating an opportunity for a broader international investor base to participate. For Tanzania, this could eventually mean a larger pool of capital competing for government securities, although wider eligibility does not automatically translate into increased investment.
International investors will still make their decisions based on the returns available in Tanzania compared with other markets, as well as exchange rate considerations, taxation, liquidity, regulatory certainty and their ability to move capital efficiently. The significance of the reform will therefore become clearer as actual participation develops.
Another important change came with the Bank of Tanzania’s launch of the Tanzania Sovereign Yield Curve in August. Although largely a technical financial market development, the yield curve provides investors and institutions with a benchmark for assessing government debt across different maturity periods.
Its importance could eventually extend beyond government borrowing. Government securities commonly provide the reference against which other debt instruments are priced, meaning a reliable sovereign benchmark can also support the development of corporate bonds and other long term financing instruments as Tanzania’s capital markets mature.
These changes are taking place against a backdrop of growing market activity. CMSA has reported increased investor participation and stronger activity across Tanzania’s primary and secondary capital markets, together with continued growth in collective investment schemes and other investment products.
The challenge now is to turn that growth into a deeper market with enough quality investments, active buyers and sellers, reliable information and liquidity to encourage investors to participate over the long term.
More state owned companies could come to market
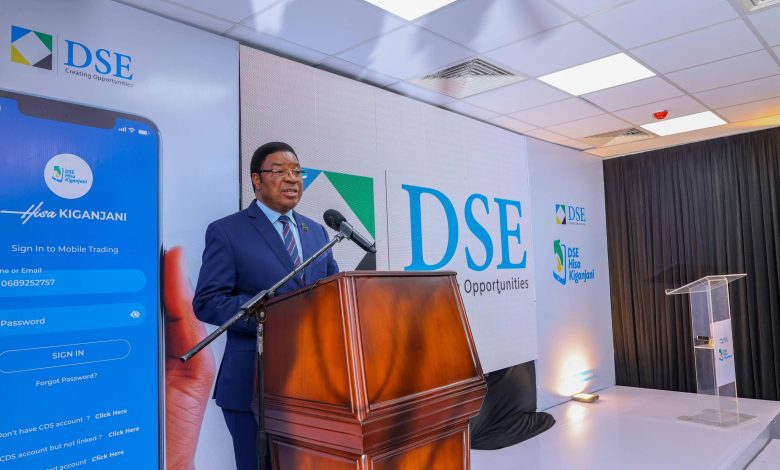
Perhaps the most visible part of Tanzania’s capital market push is the Government’s plan to bring selected state owned enterprises to the Dar es Salaam Stock Exchange.
The Office of the Treasury Registrar has been assessing public corporations to determine which could qualify for listing in the short, medium and long term. The Government has indicated that several enterprises could eventually be brought to market, although the complete list of companies under consideration has not been made public.
Tanzania Commercial Bank is among the institutions whose plans have progressed furthest. Acting Treasury Registrar Lightnes Mauki said in September that TCB had been placed in the short term category, with government procedures still required before the process could move forward.
TCB Managing Director and Chief Executive Officer Adam Mihayo has since said the bank is preparing to enter the capital market as part of efforts to strengthen its financial capacity and expand lending. He also said the move would provide an opportunity for Tanzanians to participate in ownership of the bank.
TCB already has experience raising money through Tanzania’s capital markets. In 2025, the bank launched a TZS 150 billion medium term bond programme intended to support financing for small and medium sized enterprises. Opening ownership of the bank to investors would represent a different and potentially more significant step.
The importance of the Government’s plans, however, extends beyond TCB. Bringing additional sizeable state owned enterprises to the DSE could expand the number and range of companies available to investors in a market that still has relatively few domestic listings.
It could also give public enterprises another way of raising capital rather than depending entirely on conventional government financing. For the Government, listing selected enterprises could allow it to retain an ownership interest while introducing private capital and broader shareholder participation.
There could also be implications for how listed state enterprises are governed. Public listing brings requirements around financial disclosure, reporting and accountability to shareholders, adding another layer of scrutiny to companies that have traditionally operated under government ownership.
The investment case will ultimately depend on the companies themselves. Investors will want to see their financial performance, growth prospects, governance structures and valuations, as well as understand how much ownership the Government intends to offer. A listing by itself does not make a company an attractive investment.
The wider DSE has meanwhile continued to grow in value, although market capitalisation and active trading should not be confused. A market can increase substantially in value while still experiencing relatively low trading volumes, and liquidity remains an important consideration for investors who need confidence that they can buy and sell securities when required.
What changes for investors
For Tanzanian investors, the developments could gradually create a wider range of places to put their money. Government securities, listed shares, corporate bonds, sukuk and collective investment schemes offer different ways of participating in the financial market, while additional DSE listings could give individuals and institutions access to businesses that were previously wholly owned by the state.
The opportunity is not limited to large institutional investors. Greater participation by individual Tanzanians would broaden ownership of domestic assets, but that will require investor education to develop alongside market access. Shares, bonds and investment funds behave differently, carry different risks and should not be treated as interchangeable alternatives to bank savings.
For international investors, the regulatory changes remove some of the barriers to accessing Tanzania’s government securities market. Whether that results in significant new foreign investment will depend on more than regulation. Investors will assess Tanzania alongside other emerging and frontier markets, weighing potential returns against currency exposure, liquidity and broader economic conditions.
That makes the next stage particularly important. The Government still has to determine which state owned enterprises will ultimately reach the DSE and, in each case, how much ownership will be made available. Investors will also be watching how smoothly the expanded access to government securities works in practice and whether greater participation translates into deeper trading and improved liquidity.
What is becoming clearer is the direction Tanzania is taking. Capital markets are being positioned to play a larger role in mobilising investment and financing economic activity, while both domestic and international investors are being given more ways to participate.
The real measure of these reforms will therefore not be the number of new regulations, financial instruments or proposed listings announced. It will be whether Tanzania can turn them into a market in which investors have enough choice, information and confidence to commit capital for the long term.