
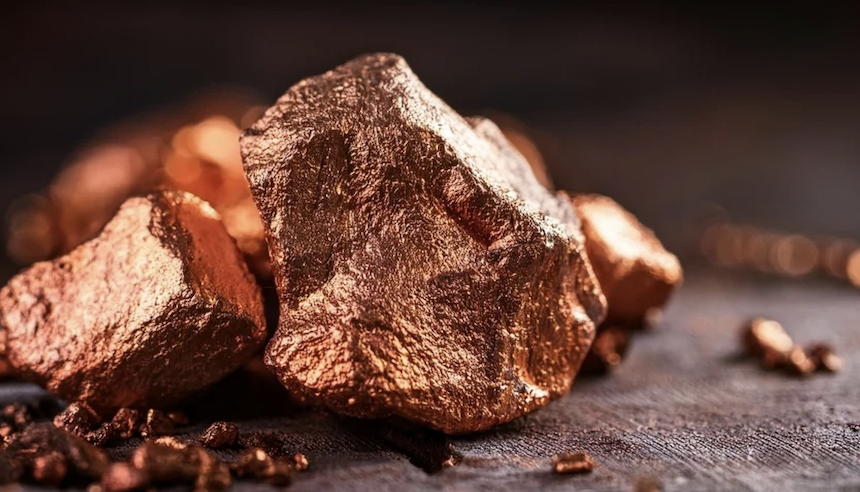
DAR ES SALAAM — Rising indicative copper prices are drawing attention to the opportunities that mineral markets can create for Tanzania, particularly as demand for the metal remains linked to electricity networks, construction, manufacturing and other infrastructure-related industries.
The Mining Commission’s indicative copper price reached US6.71perpoundonOctober10,comparedwithUS6.56 on October 2, according to its published mineral price information. The latest available figure highlights a short-term increase, although prices can change with international market conditions.
Copper is widely used in electrical wiring, power transmission equipment, electronics and industrial machinery because of its conductivity and other properties. Demand can therefore be influenced by investment in electricity networks, infrastructure and manufacturing, as well as wider changes in industrial activity.
For Tanzania, the business opportunity extends beyond selling minerals. Mining operations require transport, machinery maintenance, engineering, laboratory testing, safety equipment and other specialised services. Tanzanian companies that develop the necessary technical capacity and meet industry standards could compete to supply some of these needs.
A further opportunity lies in increasing the value retained through domestic processing where commercially and technically viable. Depending on the mineral deposit, available infrastructure and project economics, processing can create demand for skilled workers, energy, equipment, maintenance and supporting services.
However, a higher international copper price does not automatically mean higher profits for every producer. Actual returns depend on factors such as ore quality, production volumes, processing costs, transport, energy expenses, taxes and the terms of individual sales agreements.
Nor does the price increase alone establish that Tanzania has the infrastructure or commercial case for a particular new processing facility. Such decisions require detailed assessments of mineral resources, capital requirements, electricity supply, environmental considerations and access to buyers.
For local businesses, the immediate opportunity is to understand the supply chains surrounding mineral production. Firms offering reliable technical services, logistics, equipment support and other specialised capabilities may be able to participate without owning a mine.
Tanzania’s longer-term challenge is to balance competitive mineral production with greater local participation and value addition. Capturing more value will depend not simply on international prices, but on investment, technical skills, infrastructure and the ability of domestic firms to compete across the mining supply chain.

