
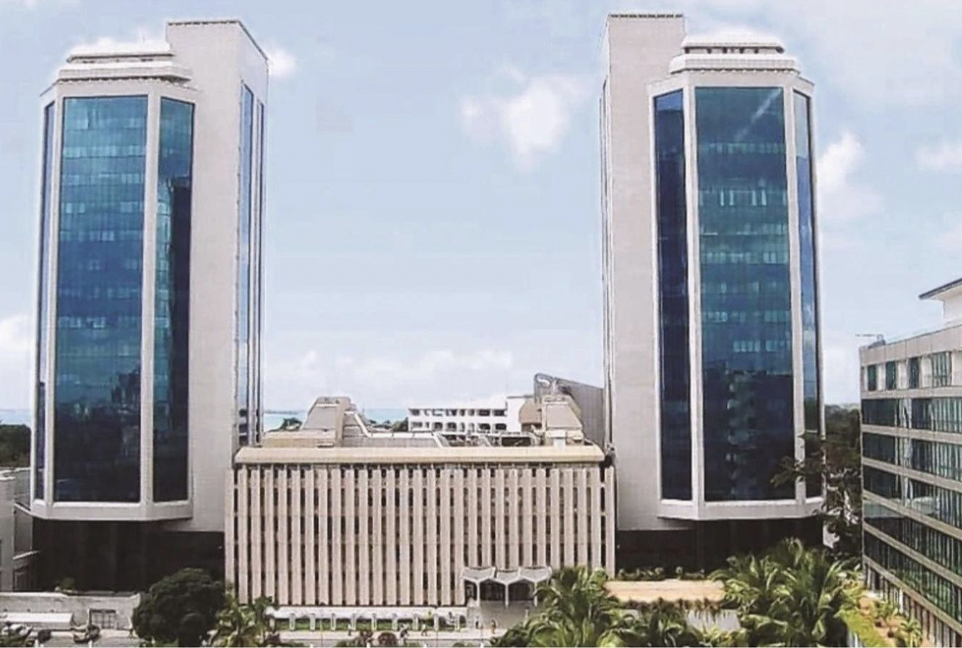
DAR ES SALAAM — The Bank of Tanzania (BoT) has maintained its Central Bank Rate (CBR) at 6.25 percent for the fourth quarter of 2026, keeping its benchmark policy rate unchanged as businesses continue to assess the cost of financing operations and expansion.
The CBR is a monetary-policy signal that helps guide short-term interest rates and conditions in the financial system. It influences the environment in which banks make lending and deposit decisions, but it does not automatically set the interest rate on every commercial loan.
For businesses, borrowing costs affect decisions ranging from purchasing inventory and paying suppliers to investing in machinery, vehicles, premises and new branches. A company relying on short-term credit may be particularly sensitive to changes in financing costs, while a business considering a long-term investment must assess whether expected returns justify the cost of borrowing.
Keeping the rate unchanged provides continuity in the central bank’s policy stance, but it does not guarantee that commercial lending rates will remain unchanged. Banks assess several factors when pricing loans, including their own funding costs, a borrower’s credit risk, collateral, loan duration and operating expenses.
This means that two businesses seeking financing may receive different terms even under the same central bank rate. Companies with reliable financial statements, predictable cash flow and clear repayment plans may be better placed to demonstrate their ability to service debt.
Businesses considering loans should compare the total cost of financing, including fees and repayment schedules, rather than focusing only on the advertised interest rate. They should also test whether their cash flow could support repayments if sales fall or operating costs rise.
For banks, the policy rate forms part of the wider economic environment in which they balance lending, deposits and risk. For businesses, its practical impact will depend on how changes in monetary conditions pass through to individual loan products.
The BoT’s decision is therefore an important indicator to monitor, but not a direct forecast of what every borrower will pay. Companies planning expansion should assess actual loan offers and their own financial position before committing to new financing.

